My Sister Asked Me to Co-Sign Her Student Loan—Then She Defaulted and I Got a Letter from the IRS for $80,000
The Letter That Tore My Life Apart
The envelope from the IRS was thin, the kind that usually means bad news. I opened it on a Tuesday morning in March, standing in my kitchen in Boise, Idaho, with a cup of coffee going cold in my hand. The letter said I owed $80,000 in unpaid student loan debt—debt I had co-signed for my younger sister, Melissa, eight years earlier. I hadn’t heard from her in six months. The last time we spoke, she’d promised she was making payments. The letter proved she hadn’t made a single one in over two years.
My hands shook as I read the words: “You are personally liable for the outstanding balance.” I had a mortgage, a ten-year-old son, and a job as a high school English teacher that paid $52,000 a year. There was no way I could cover $80,000. I called Melissa immediately. It went straight to voicemail. I called again. Same. I texted. Nothing. That’s when I realized my sister hadn’t just defaulted on a loan. She had disappeared.
The Promise I Couldn’t Refuse
Eight years earlier, Melissa had been accepted to a private university in Oregon to study graphic design. She was 22, bright, and full of big dreams. Our parents had passed away years before, and I was the only family she had left. She’d called me crying, saying the financial aid package wasn’t enough. She needed a co-signer for a $60,000 loan. I was 30, newly married, and we’d just put a down payment on our first house. My husband, David, was hesitant. “Co-signing is risky,” he’d said. But Melissa was my baby sister. I remembered how she’d held my hand at Mom’s funeral. I signed the papers.
For the first few years, Melissa made her payments on time. She graduated, got a job at a design firm in Portland, and seemed to be doing well. She’d send me photos of her apartment, her friends, her life. I was proud of her. Then the payments started getting spotty. She’d miss one, then catch up. She’d promise to pay me back for the ones I covered. She never did. Each time, I told myself it was temporary. She was young. She’d figure it out. I didn’t want to be the overbearing older sister.
By year five, the loan was in forbearance. By year six, Melissa had stopped answering my calls. I’d get a text every few months: “Sorry, been busy! Will call soon.” She never did. I started to worry, but I didn’t want to push. Then the IRS letter arrived, and I realized my worry had been naive. This wasn’t about forgetfulness. This was about avoidance.
The Search for the Truth
I couldn’t afford a lawyer, so I started doing my own digging. I called the loan servicer and requested a full payment history. What I found made my stomach drop. Melissa had made exactly three payments in the last two years—all for less than $50. She’d been in default for 18 months, and the servicer had sent multiple notices to her last known address. She’d ignored every single one. Meanwhile, I’d been receiving nothing. I was the co-signer, but the servicer had never contacted me until the debt was sold to a collection agency and reported to the IRS as taxable income.
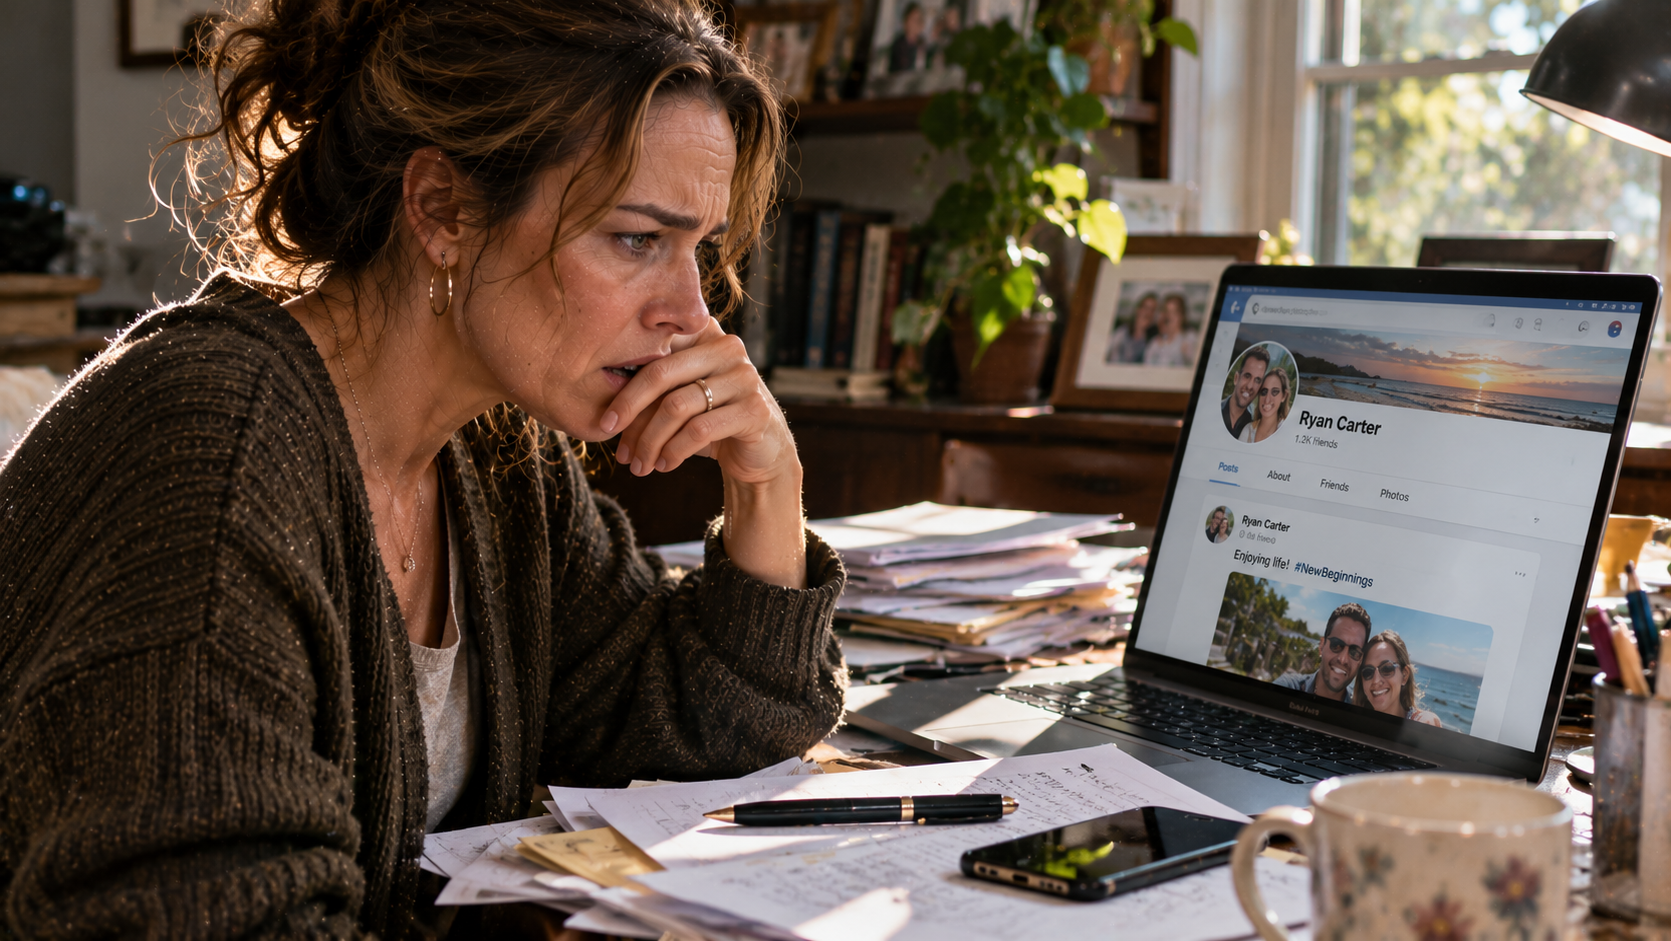
I needed to find Melissa. I called her old employer—she’d left two years ago. I called her friends—they hadn’t heard from her in months. I even drove to Portland and knocked on her last known apartment door. The new tenant had no idea who she was. I was about to give up when I remembered she’d once mentioned a boyfriend named Aaron. I found him on social media. His profile was private, but his profile picture showed him standing in front of a house with a sign that read “Sold!” The address was visible in the background.
I drove to the address—a beautiful four-bedroom house in a suburb of Portland. A brand-new SUV sat in the driveway. I knocked. Melissa answered. She was wearing a designer dress and holding a glass of wine. Her face went pale when she saw me. “What are you doing here?” she whispered. I held up the IRS letter. “We need to talk,” I said.
Inside, the house was immaculate. Original art on the walls, a kitchen with marble countertops. I asked her how she could afford all this while defaulting on her loan. She stammered, then admitted the truth: she’d been working as a freelance designer and making good money—over $120,000 a year. But she’d been hiding it. She’d put her income in a separate bank account, one she never mentioned to the loan servicer. She’d bought the house with Aaron, but only his name was on the mortgage. She’d been living a life of luxury while I struggled to pay my bills.
“I was going to pay it back,” she said. “I just needed more time.” I asked her why she’d ignored the notices. She looked away. “I thought if I ignored it, it would go away.” I told her it hadn’t gone away. It had landed on my doorstep. She offered to make a payment plan—$500 a month. I calculated: at that rate, it would take me over 13 years to pay off the $80,000, plus interest. I told her it wasn’t good enough. She shrugged. “That’s all I can do.” I left feeling more alone than ever.
The Evidence That Changed Everything
Back home, I couldn’t sleep. I kept thinking about that house, that car, that designer dress. Melissa had money—she just didn’t want to use it to pay her debts. I started researching co-signer rights. I learned that in Idaho, a co-signer who pays a debt is entitled to sue the primary borrower for reimbursement. I also learned that if I could prove Melissa had the means to pay but chose not to, a court might award me punitive damages. I needed evidence.
I hired a private investigator—a retired cop named Frank who charged $75 an hour. It was a gamble, but I didn’t have a choice. Within a week, Frank had pulled Melissa’s financial records. She had over $200,000 in a savings account, a 401(k) worth $150,000, and a joint account with Aaron that showed regular deposits from her freelance business. She’d been hiding assets for years. Frank also found something else: Melissa had co-signed a loan for Aaron’s business—a loan that had also gone into default. She’d been lying to everyone.
I took the evidence to a lawyer, a sharp woman named Patricia who specialized in consumer protection. She reviewed the documents and smiled. “We have a case,” she said. “Not just for reimbursement, but for fraud. She concealed assets while you were on the hook.” We filed a lawsuit in Multnomah County Court. I asked for the full $80,000 plus legal fees and punitive damages. Melissa was served at her home. She called me screaming, calling me a traitor, saying I was destroying her family. I told her she’d destroyed mine first.
The Courtroom Reckoning
The trial lasted three days. Melissa showed up with a lawyer, but her defense was weak. She claimed she’d been struggling financially, but Patricia presented the bank statements, the savings account, the joint account. Melissa’s lawyer argued that she’d planned to pay eventually, but the judge wasn’t convinced. “Ms. Carter,” he said, “you had the means to pay and chose not to. That’s not struggle. That’s evasion.”
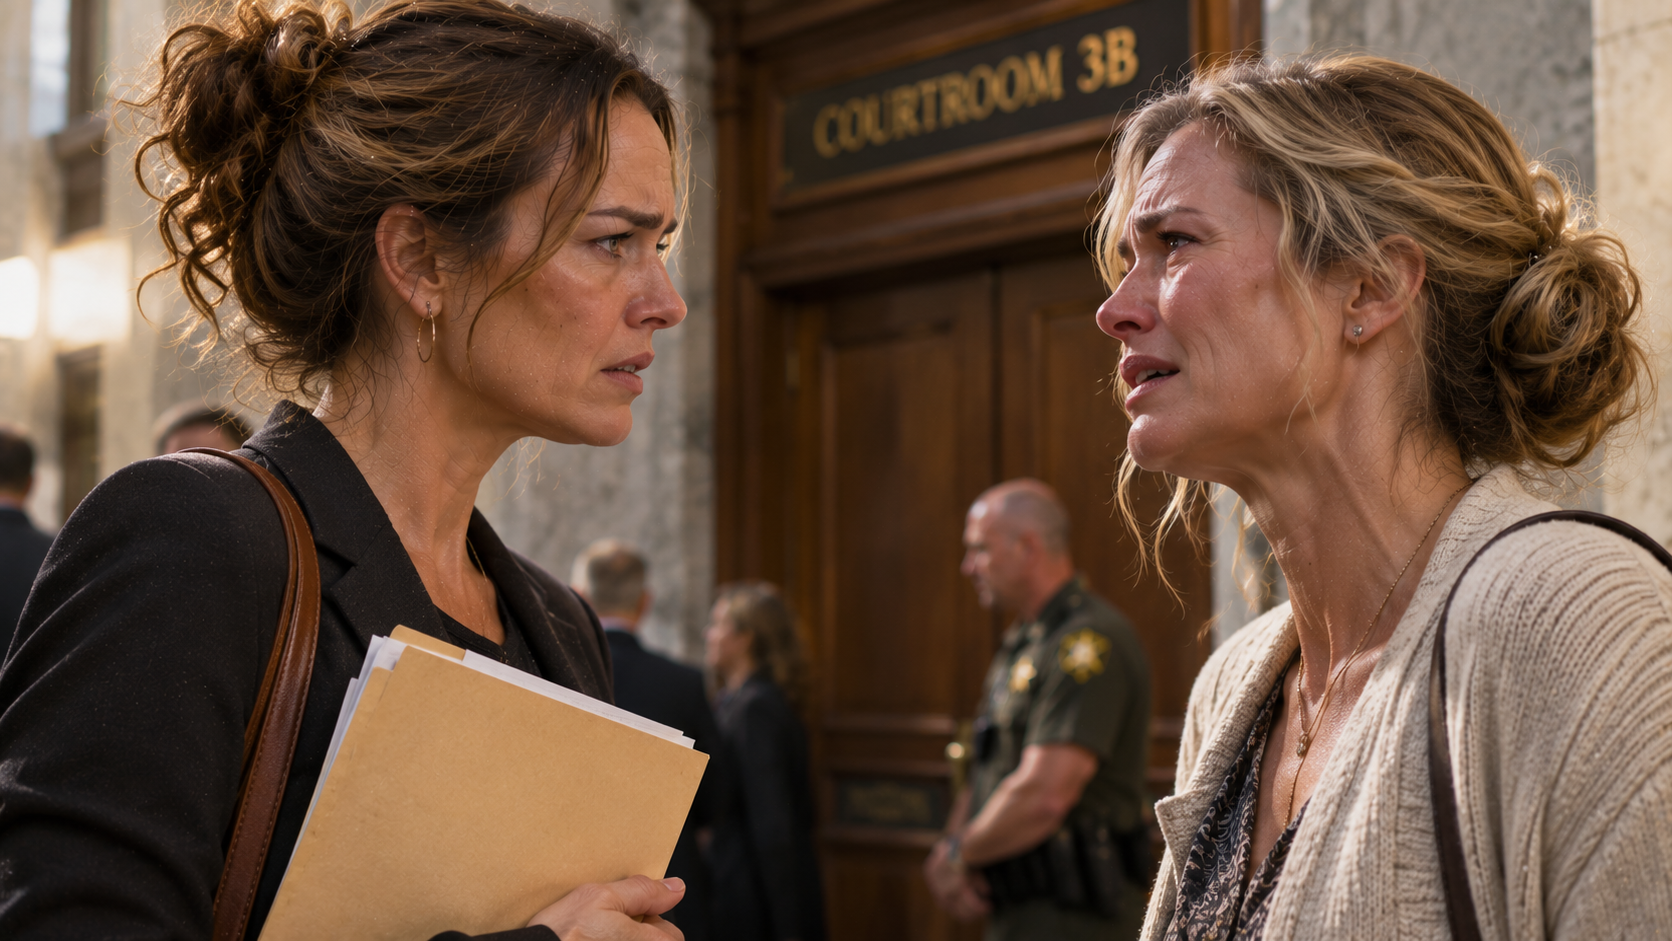
The judge ruled in my favor, awarding me the full $80,000 plus $15,000 in legal fees. He also ordered Melissa to pay $10,000 in punitive damages. She broke down in tears, but I felt nothing. After the verdict, she approached me in the hallway. “I’m your sister,” she said. “How could you do this?” I looked her in the eye. “You stopped being my sister the moment you decided my life didn’t matter.”
Melissa had to sell her house to pay the judgment. Aaron left her—turns out he hadn’t known about the hidden accounts either. She moved into a small apartment and took a job at a local design firm. I heard through a mutual friend that she was struggling, but I didn’t reach out. I’d spent years covering for her, and I was done.
What I Learned About Trust and Boundaries
It’s been two years since the trial. I used the settlement to pay off the IRS debt and put the rest into my son’s college fund. I’m still teaching, still living in the same house. David and I are stronger than ever—he stood by me through the whole ordeal. I don’t regret co-signing for Melissa, because it taught me a hard lesson: love doesn’t mean sacrificing your own future for someone who won’t do the same for you.
I haven’t spoken to Melissa since the verdict. She sent me a letter last Christmas, asking for forgiveness. I read it, then put it in a drawer. Maybe one day I’ll be ready. But for now, I’m focused on my own family—the one I built, not the one I was born into. My son asked me recently why I don’t talk to Aunt Melissa anymore. I told him the truth: sometimes people make choices that hurt us, and we have to protect ourselves. He nodded, then went back to his homework. I hope he never has to learn that lesson the way I did.
If there’s one thing I want people to take away from my story, it’s this: co-signing a loan is not a favor. It’s a legal contract. Before you sign, ask yourself if you’re willing to pay the entire debt yourself. Because you might have to. And if you do, don’t be afraid to fight back. You have rights. Use them.
Recommended Stories
At My Grandfather’s Will Reading, a Stranger Claimed to Be His Daughter—Then the DNA Test Showed She Was Actually My Half-Sister, and My Father Knew All Along
A stranger at my grandfather's will reading claimed to be his daughter. Then the DNA test revealed she was actually...
My Stepmother Sold My College Fund for a Beach House—Then a Stranger Showed Up at Her Door with a Shocking Contract
She thought she'd gotten away with it—until a stranger with a briefcase knocked on her door. The contract inside revealed...
I Gave Up My Career to Care for My Ailing Grandmother—Then My Cousin Sold Her House and Kept the $500,000
I quit my dream job to care for my dying grandmother. Then my cousin forged my signature, sold her house,...